

Export essentials
Subscribe to our newsletter
Get the latest updates, insights, and tips delivered straight to your inbox.
Last updated: 10 November 2026
What are export payment terms? Export payment terms are the conditions that decide when and how an overseas buyer pays an Indian exporter. The most common export payment terms are advance payment, letter of credit (LC), documents against payment (D/P), documents against acceptance (D/A), open account and consignment. Advance payment and a confirmed LC are the safest for the exporter, while open account and consignment carry the most risk.
The term you agree on decides how much risk you carry, how quickly the money reaches you and how much paperwork you handle. It also decides whether you can stay within the RBI time limit for bringing export money back to India. This guide explains every type in plain language, shows which terms are safest, covers the latest RBI rules on export payments and lists the documents you need. We also look at how the money actually reaches your bank account once the terms are agreed, which is where a platform like Infinity fits in.
TL;DR
What are export payment terms? - They are the agreed conditions for when and how a foreign buyer pays you for goods or services. They are written into your contract and invoice.
What are the types of export payment terms? - Advance payment, letter of credit (LC), documents against payment (D/P, also called CAD), documents against acceptance (D/A), open account and consignment.
What are the most common export payment terms for Indian businesses? - Advance payment, LCs, D/P, D/A and open account are used most. Many exporters mix them, such as part advance and the balance against documents.
Which export payment terms are safest for exporters in India? - Full advance payment is the safest, followed by a confirmed irrevocable LC. Open account and consignment are the riskiest.
What are the RBI rules for export payments? - Under the FEMA Export and Import Regulations, 2026, in force from 1 October 2026, export proceeds must generally be realised and repatriated within 9 months. Payment should come through an Authorised Dealer bank.
How do you choose the right term? - Match it to buyer trust, order value, country risk and your cash flow, and make sure the credit period fits inside the RBI time limit.
What Are Export Payment Terms?
Export payment terms are the conditions agreed between an exporter and a buyer on when payment is due, how it will be made and what must happen before the money is released. They are written into the sales contract, the proforma invoice and the commercial invoice.
They matter for four reasons:
Risk: They decide who carries the risk of late payment or non-payment.
Cash flow: They decide whether you are paid before shipping, at shipping or weeks later.
Competitiveness: Buyers like flexible credit terms. Terms that are too strict can cost you the order.
Compliance: They decide which documents your bank needs and how the RBI realisation clock works for your payment.
Payment Terms vs Incoterms
Payment terms decide when and how you get paid. Incoterms, such as FOB, CIF and EXW, decide who arranges shipping and insurance, who pays freight and at what point the risk passes from seller to buyer. They are agreed together in the same contract, but they are different things.
For example, a sale on FOB terms with payment by LC means the buyer takes the risk once the goods are loaded on the ship, and you get paid when the bank accepts your documents. New exporters often mix the two up, so it helps to state both clearly in every contract.
What Are the Types of Export Payment Terms?
There are six main types of export payment terms: advance payment, letter of credit, documents against payment, documents against acceptance, open account and consignment. They run from the safest for the exporter (advance payment) to the riskiest (open account and consignment).

Advance payment (cash in advance)
Letter of credit (LC)
Documents against payment (D/P or CAD)
Documents against acceptance (D/A)
Open account
Consignment
1. Advance Payment (Cash in Advance)
In advance payment, the buyer pays part or all of the invoice before you ship. It is the safest export payment term for an exporter because you hold the money before the goods leave India.
How it works: You send a proforma invoice, the buyer transfers the money and you ship once the funds arrive. Many deals use a part advance, for example 30% upfront and the balance on shipment or against documents.
Risk for the exporter: Almost none. The risk moves to the buyer, who may hesitate to pay in advance to a new supplier.
Cost: Low. You only pay the charges for receiving the money.
Best used when: Goods are in high demand, products are custom made, the buyer is new or the order value is small.
Because advance payments usually arrive as international transfers, what you pay to receive them matters. With Infinity, the fee is 0.5% all-inclusive with no separate FX markup, and your FIRA is free.
2. Letter of Credit (LC)
A letter of credit is a promise from the buyer's bank to pay you, as long as you submit the documents the LC asks for, exactly as stated. It is one of the safest export payment terms because you depend on a bank, not only on the buyer.
How it works: The buyer applies to their bank, which issues the LC and sends it to your bank. You ship the goods and submit the required documents. The bank checks them and pays either immediately (sight LC) or on a fixed later date (usance LC).
Main types of LC:
Irrevocable LC: Cannot be changed or cancelled without everyone's consent.
Confirmed LC: A second bank, usually in your country, adds its own guarantee. This protects you if the issuing bank or its country fails to pay.
Standby LC: A backup guarantee that is used only if the buyer fails to pay.
Sight and usance LC: Sight pays when documents are presented. Usance pays after a set period.
Risk for the exporter: Low, especially with a confirmed LC. The main risk is paperwork. Even a small mismatch in a document, such as a wrong date or spelling, can make the bank refuse payment.
Cost: High. There are fees for issuing, advising, confirming and amending the LC, and preparing documents takes time.
Best used when: Orders are large, the buyer is new or the buyer's country is risky.
For a deeper explanation, read our guide on cash against documents and letters of credit.
3. Documents Against Payment (D/P or CAD)
In documents against payment (D/P), also called cash against documents (CAD), your bank sends the shipping documents to the buyer's bank, which hands them over only when the buyer pays. The buyer cannot collect the goods without paying first.
How it works: You ship the goods and give the documents to your bank with collection instructions. Your bank forwards them to the buyer's bank. The buyer pays, receives the documents and clears the goods.
Risk for the exporter: Medium. The bank does not guarantee payment. If the buyer refuses to pay, the goods sit at the port and you must find another buyer or bring them back, which costs money.
Cost: Lower than an LC because banks only handle the documents.
Best used when: You know the buyer, the order is moderate in size and the goods can be resold if the deal fails.
4. Documents Against Acceptance (D/A)
In documents against acceptance (D/A), the buyer receives the shipping documents after accepting a bill of exchange, which is a written promise to pay on a fixed future date such as 30, 60 or 90 days. The buyer gets the goods first and pays later.
How it works: You ship and send the documents and the bill of exchange through your bank. The buyer accepts the bill, gets the documents and pays on the due date.
Risk for the exporter: Medium to high. The goods are released before payment, so everything depends on the buyer honouring the accepted bill.
Cost: Low to medium, mostly bank collection charges.
Best used when: The buyer is a trusted repeat customer who needs time to pay.
Want to see how D/A and D/P compare in detail? Read our guide on D/A vs D/P in international sales.
5. Open Account
On open account, you ship the goods and send the documents directly to the buyer, who pays on an agreed date, usually 30 to 90 days later. It is one of the riskiest export payment terms because everything depends on the buyer paying on time.
How it works: There is no bank guarantee and no document control. You trust the buyer to pay the invoice by the due date.
Risk for the exporter: High. You face the risk of delayed payment, non-payment and disputes. The credit period must also fit within the RBI time limit for realising export proceeds.
Reducing the risk: Many Indian exporters use export credit insurance from ECGC (Export Credit Guarantee Corporation of India), which can cover non-payment by the buyer in certain situations. Check the cover and cost before you ship.
Cost: Bank costs are the lowest, but you carry the cost of waiting for your money.
Best used when: The buyer is a long-term, trusted customer, or a large buyer who insists on open account.
When the buyer pays an open account invoice, Infinity gives you bank details in multiple currencies to share with them, and your FIRA is generated for you after the payment arrives.
6. Consignment
In consignment, you send goods to an agent or distributor abroad, who sells them and pays you after the sale. You keep ownership of the goods until they are sold, which makes this term slow and risky for the exporter.
How it works: The goods are shipped to the consignee, who stores and sells them. You are paid only after they are sold.
Risk for the exporter: High. Stock may stay unsold, payment may be delayed and the goods can be hard to recover.
RBI note: Ask your Authorised Dealer bank how the realisation period is counted for your consignment or warehouse export, because exports through overseas warehouses follow a separate starting point.
Cost: You usually bear storage, insurance, freight and the cost of returning unsold goods.
Best used when: You want to test a new market or launch a new product with a trusted consignee.
What Are the Most Common Export Payment Terms Used by Indian Businesses?
Indian exporters mainly use advance payment, letters of credit, D/P, D/A and open account. The choice depends on how well they know the buyer, how big the order is and how risky the country is. Many exporters also mix terms within one deal.
Here is how it usually works in practice:
New buyer: Advance payment or an LC. A part advance with the balance against documents is also common.
Repeat buyer: D/A or open account with an agreed credit limit.
Large order: An LC, ideally confirmed.
Small order or small exporter (MSMEs): Advance or part advance, since it keeps paperwork light and removes payment risk.
Freelancers and service exporters follow a similar pattern. They usually invoice the client and receive a bank transfer, either in advance or after delivery. The same RBI time limit applies to services, so credit periods should be kept short.
Which Export Payment Terms Are the Safest for Exporters in India?
Full advance payment is the safest export payment term for an exporter, followed by a confirmed irrevocable letter of credit. Open account and consignment are the riskiest because you ship before you are paid.
From safest to riskiest:
Advance payment: You hold the money before shipping.
Confirmed irrevocable LC: Two banks stand behind the payment.
Irrevocable LC (unconfirmed): One bank guarantees payment.
D/P (CAD): The buyer must pay to get the documents.
D/A: The buyer gets the documents first and pays later.
Open account: You ship first and trust the buyer to pay.
Consignment: You are paid only after the goods are sold.
Payment term | Risk for exporter | Bank cost | When you get paid | Best for |
Advance payment | Very low | Low | Before shipment | New buyers, custom or high-demand goods |
Confirmed irrevocable LC | Low | High | After documents are accepted | Large orders, risky markets |
Irrevocable LC (unconfirmed) | Low to medium | High | After documents are accepted | Reliable issuing banks |
D/P (CAD) | Medium | Low to medium | When the buyer pays for documents | Known buyers, moderate orders |
D/A | Medium to high | Low to medium | On the due date of the accepted bill | Trusted repeat buyers |
Open account | High | Lowest | On the agreed credit date | Long-term trusted buyers |
Consignment | Very high | Varies | After goods are sold | Testing a new market |
The safest term for you is not always the one your buyer will accept. If you have to offer D/A or open account to win the order, ECGC export credit insurance is a common way to reduce the risk.
What Documents and Proof of Payment Do Exporters Need?
The core documents for an export payment are the commercial invoice, packing list, shipping bill, bill of lading or airway bill, export declaration and FIRA. Under an LC or a bank collection, your bank may ask for a few more.
Commercial invoice: The bill for the goods or services, showing buyer, value, currency and payment terms.
Packing list: Details of what is in each package, with weights and dimensions.
Shipping bill: The customs document filed for exporting goods from India.
Bill of lading or airway bill: The transport document issued by the carrier. It acts as a receipt for the goods and is needed for D/P, D/A and LC payments.
Export declaration form (EDF): The declaration of the export value and expected payment, which is matched with the money you receive.
Insurance certificate: Needed when the sale terms or LC require insurance cover.
Certificate of origin: Needed when the buyer's country or the LC asks for proof of where the goods were made.
Bill of exchange and LC documents: Needed for D/A and LC transactions, exactly as the LC or bank instructs.
FIRA (Foreign Inward Remittance Advice): Proof that the money was received from abroad. Infinity generates it automatically and it is free.
For a full walkthrough, read our guide on export documents Indian exporters need.
How to Choose the Right Export Payment Term
Choose the safest payment term your buyer will accept. Match it to how well you know the buyer, the order value, country risk, the product and your cash flow, and make sure the credit period fits within the RBI time limit.
Follow these steps:
Check the buyer. For a new buyer, choose advance payment or an LC. For a known buyer, D/A or open account can work. Run a credit check before giving any credit.
Check the order value. Large orders suit an LC. Smaller orders suit advance payment or D/P.
Check the country and bank risk. In unstable markets, choose a confirmed LC or advance payment.
Check the product. Perishable or custom goods suit advance payment or an LC. Standard goods that are easy to resell can work with D/P.
Check your cash flow. If you cannot wait 60 to 90 days for payment, ask for an advance or part advance.
Align with your Incoterm. The Incoterm decides when risk passes to the buyer, so set it together with the payment term.
Check the RBI window. The credit period plus shipping time must fit inside the realisation period.
Consider a mix. A part advance with the balance against documents often satisfies both sides.
Quick picks by situation:
New buyer, large order: Confirmed irrevocable LC.
New buyer, small order: Full advance payment.
Repeat buyer with steady orders: D/A or open account, ideally with ECGC cover.
Testing a new market: Consignment with a trusted consignee.
How Does Infinity Help Receive International Payments?
Your payment term decides when the buyer pays. Infinity helps with the next step, getting that payment into your Indian bank account at a clear, low cost, with the compliance paperwork done. Infinity is a global payments platform for Indian exporters, freelancers, agencies and startups, and payments are processed through licensed banking partners regulated by the RBI.
Low, clear fee: 0.5% all-inclusive, with no separate FX markup and no additional GST.
Free FIRA: Generated automatically for your payments.
Fast settlement: Within 24 hours.
Wide reach: Supports 50+ currencies and 160+ countries.
Dedicated account manager: A person to help you when something needs sorting out.
Mobile app: Track and manage your payments on the go.
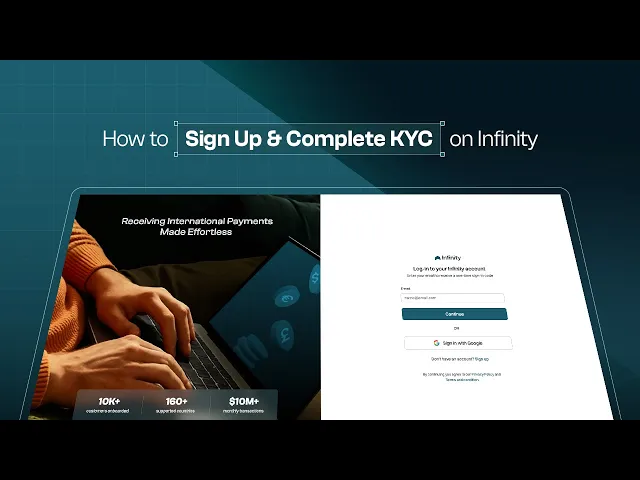
Getting started takes four steps:
Sign up in about 2 minutes.
Complete verification and KYC, which is done the same day.
Receive bank details in multiple currencies.
Share them with your buyers and start receiving international payments.
Watch this video for a step-by-step guide on how to start with Infinity.
Whichever payment term you choose, a clear receiving process helps you stay within the RBI time limit and keeps your records clean.
FAQs on Export Payment Terms
1. What are export payment terms?
Export payment terms are the agreed conditions for when and how a foreign buyer pays an exporter for goods or services. They cover the timing of payment, the method and any documents or conditions needed before the money is released.
2. What are the common export payment terms used in international trade?
The common terms are advance payment, letter of credit, documents against payment (D/P), documents against acceptance (D/A), open account and consignment. Letters of credit are common for large or risky deals, while open account is common between trusted trading partners.
3. What are the most common export payment terms for Indian businesses?
Indian businesses mostly use advance payment, LCs, D/P, D/A and open account. New buyers are usually handled with advance payment or an LC, and repeat buyers with D/A or open account.
4. What export payment term options are safest for exporters in India?
Full advance payment is the safest, followed by a confirmed irrevocable LC. Both mean you are paid, or a bank has promised to pay you, before you take on buyer risk.
5. What are the types of payment terms?
The main types are advance payment, letter of credit, documents against payment, documents against acceptance, open account and consignment. They differ in who carries the risk and when you receive the money.
6. What are the RBI rules for export payments?
Under the FEMA Export and Import Regulations, 2026, in force from 1 October 2026, exporters must generally realise and repatriate export proceeds within 9 months, or 12 months if the export is invoiced or settled in rupees. Payment should come through an Authorised Dealer bank, and your bank can allow an extension if the delay is genuine.
7. What is the difference between D/A and D/P?
In D/P, the buyer must pay before getting the shipping documents. In D/A, the buyer gets the documents after accepting a bill of exchange and pays on a later date. D/P is safer for the exporter because the goods are not released until payment is made.
8. What does CAD mean in export payment terms?
In exports, CAD usually means cash against documents. It works like D/P, where the buyer pays the bank to receive the shipping documents.
9. Which payment term is best for new buyers?
Advance payment or a confirmed irrevocable LC. Both protect you when you have no payment history with the buyer.
10. How long do exporters have to receive export payments in India?
The general period is 9 months from the date of shipment for goods, or from the invoice date for services and software. It is 12 months for exports invoiced or settled in rupees. Your AD bank can allow more time if the delay has genuine reasons.
11. What is the difference between Incoterms and export payment terms?
Payment terms decide when and how you get paid. Incoterms decide who arranges shipping and insurance and when risk passes from seller to buyer. You should set both in the same contract.